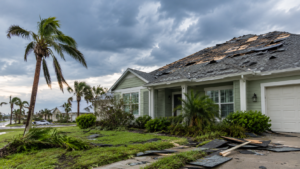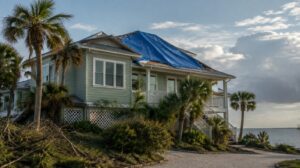
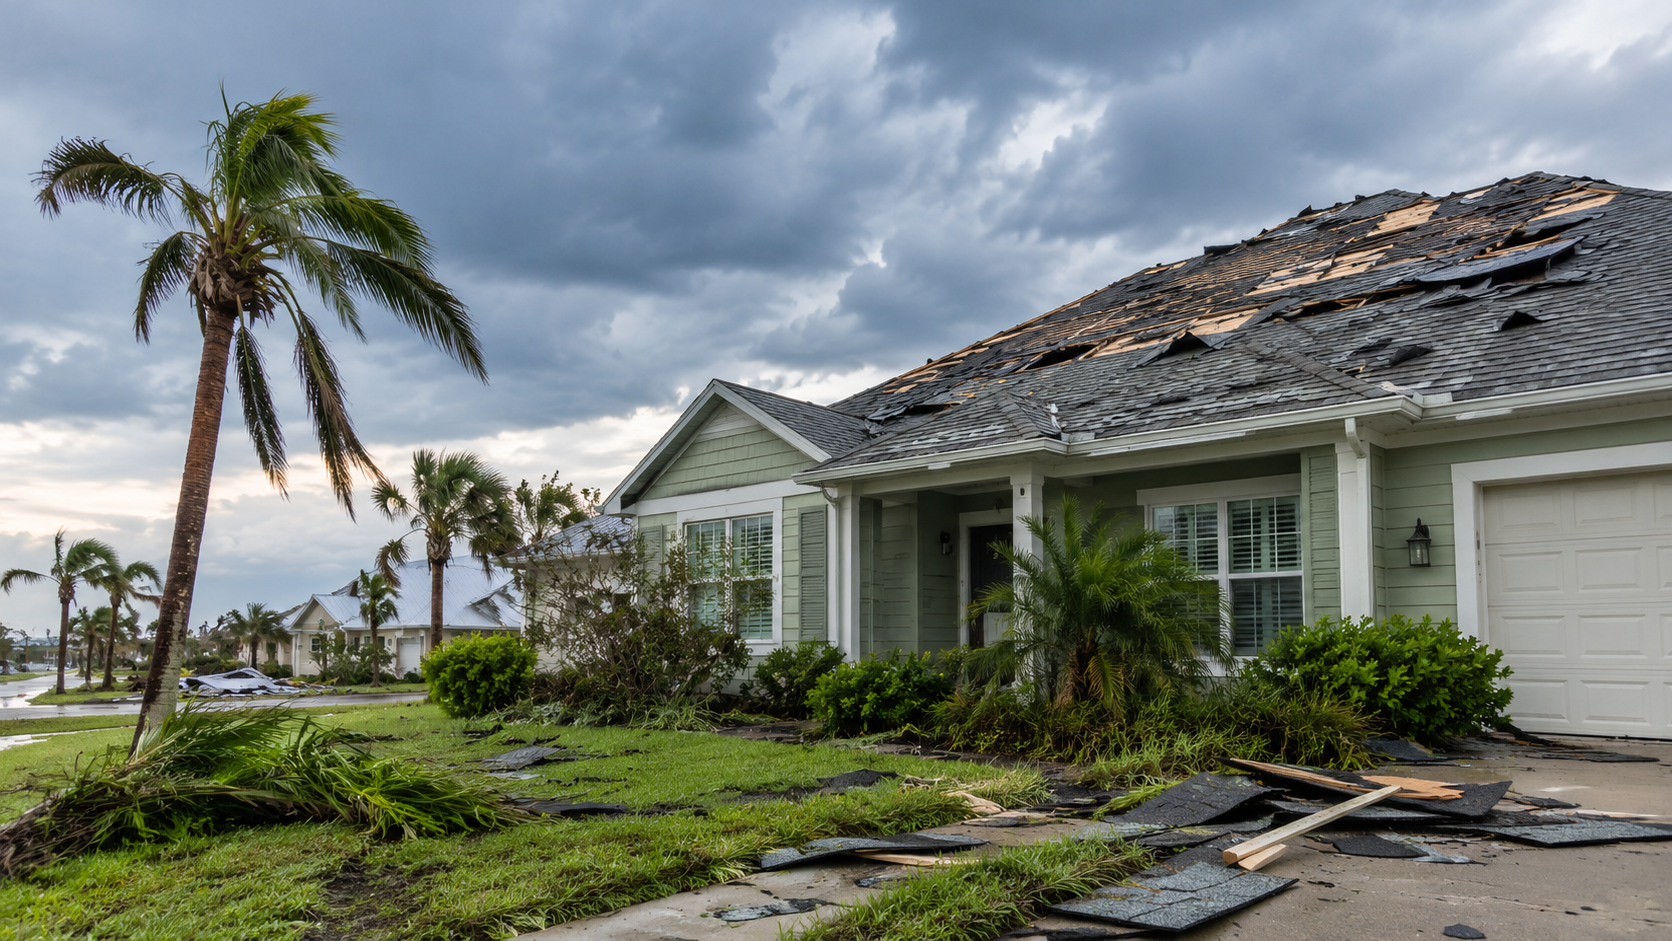
Hurricane Isaias caused widespread damage across Florida’s Panhandle. For many homeowners, the storm was only the beginning of the problem.
Now, as insurance claims move through the system, new figures raise an important question: What happens when you report damage to your insurance company and receive no payment?
According to reporting by WUSF on October 25, approximately 55,000 insurance claims had been filed in Florida following Hurricane Isaias, with estimated insured losses approaching $582 million. Nearly 8,500 claims had been closed without payment at the time of the report.
Those numbers do not mean every unpaid claim was wrongly handled. Some claims may have been closed for administrative reasons, while others may involve coverage disputes or other issues. But if your home was damaged and your claim has not resulted in a payment, it is worth understanding what happens next.
If your Hurricane Isaias insurance claim was denied, closed without payment, or underpaid, you may have options.
Why Are Some Hurricane Isaias Claims Closing Without Payment?
There is an important difference between a claim that has not yet been paid and one that has been closed without payment.
An open claim may still be under investigation. The insurance company might be reviewing estimates, requesting documents, arranging an inspection, or determining the extent of the damage.
A claim closed without payment is different. It means the insurer has closed the claim without recording a payment, but the reason for that decision matters.
Possible explanations include:
- Administrative issues. A claim may have been opened in error, duplicated, or closed because of a communication problem.
- A coverage dispute. The insurer may conclude that the reported damage is not covered under the policy.
- Disagreement over the cause of damage. The insurance company may attribute roof damage or water intrusion to wear and tear, deterioration, or another cause rather than a covered storm event.
- Insufficient documentation. The insurer may believe it lacks the information needed to evaluate the claim.
- Disagreement over the amount of damage. The insurer may determine that the covered damage does not justify a payment after applicable deductibles or other policy provisions.
These situations are not interchangeable. A claim closed because it was a duplicate is very different from a claim denied because the insurer believes the damage is excluded.
The first step is to find out exactly why your claim was closed and whether the decision can be challenged.
What If Your Home Was Damaged but the Insurance Company Says It Won’t Pay?
Imagine that Hurricane Isaias damaged your roof. You noticed missing shingles, water stains on the ceiling, and leaks that had not been present before the storm.
You reported the damage and cooperated with the inspection. Later, the insurance company informed you that it would not issue a payment.
What should you do?
Start by reviewing the insurer’s explanation. Does it say the damage was not covered? Does it attribute the problem to an existing condition? Was the claim closed because the insurer says it never received requested information?
The answer can help determine what evidence may be needed and what options are available.
For example, photographs, contractor estimates, inspection reports, repair invoices, and records of communications with the insurer may help clarify what happened. Depending on the dispute, an additional inspection or expert evaluation may also be appropriate.
You should not assume that every denial is improper. But you also should not assume that an insurance company’s decision is necessarily correct simply because it has issued a denial letter.
What If the Insurance Company Paid You, but Not Enough to Repair Your Home?
Not every problem involves a complete denial.
Some homeowners receive an insurance payment only to discover that the amount falls short of the actual repair costs.
A roofing contractor might identify damage that the insurance company’s estimate omitted. Water damage inside the home may require more extensive work than the initial inspection reflected. The insurer and contractor may also disagree about labor, materials, or the scope of repairs.
In these situations, it may be appropriate to ask the insurer to review additional documentation or consider a supplemental claim.
Whether additional payment is available depends on the policy, the covered damage, and the supporting evidence. A higher contractor estimate alone does not guarantee additional benefits, but meaningful differences between estimates deserve careful review.
What Should Florida Homeowners Do Right Now?
If Hurricane Isaias damaged your property and your insurance claim remains unresolved, or you received a denial or an inadequate payment, consider these steps.
1. Get the insurance company’s decision in writing.
Request the claim status, the reason for any denial or closure, and the relevant estimate or coverage explanation. Keep copies of all correspondence.
2. Document the damage.
Take photographs and videos of affected areas. Keep contractor estimates, invoices, inspection reports, and receipts for temporary repairs. Take reasonable steps to protect your home from additional damage.
3. Keep a record of your communications.
Write down when you contacted the insurer, who you spoke with, what was discussed, and any documents requested or provided.
4. Do not ignore deadlines.
Florida law imposes deadlines on property insurance claims, and the applicable requirements can depend on the type of claim and the date of loss. Do not assume that an ongoing conversation with your insurer extends a filing deadline.
5. Consider getting legal advice.
If you believe the insurance company has improperly denied your claim, failed to account for covered damage, or delayed resolving a dispute, an attorney who handles Florida property insurance claims can review the situation and explain your options.
How Eisenstein Legal Helps Homeowners With Hurricane Claims
Dealing with storm damage is stressful enough without having to fight to understand your insurance company’s decision.
Eisenstein Legal, PLLC represents Florida homeowners and business property owners in disputes involving denied, delayed, and underpaid property insurance claims.
We review the insurance company’s position, evaluate the available evidence, and work to pursue the benefits our clients may be entitled to recover under their policies.
We believe clients deserve direct access to their attorneys. Our boutique firm works with clients throughout the claims process, including taking over communications with the insurance company as we work toward a resolution.
We serve property owners across Florida, including communities throughout the Panhandle, including Pensacola, Milton, Crestview, Panama City, and Tallahassee. Our attorneys speak English and Spanish.
We offer free initial consultations and handle qualifying cases on a contingency-fee basis. Our fee arrangement is explained before you decide how to proceed.
Is Your Hurricane Isaias Claim Still Unresolved?
If your home suffered storm damage and your insurance claim was denied, closed without payment, delayed, or underpaid, you do not have to navigate the situation alone. Contact us for a free consultation.