Finding damage to your home or business is stressful enough. But opening a denial letter from your insurance company? That is a different level of frustration.
If your property damage claim was denied, you are not alone. With insurance companies increasingly using automated systems to process claims, auto-denials are on the rise.
But a denial is not the final word. Here are the three most common reasons insurers reject property claims and how a property damage attorney can help you fight back.
3 Common Reasons for Insurance Claim Denials
1. The “Wear and Tear” Loophole
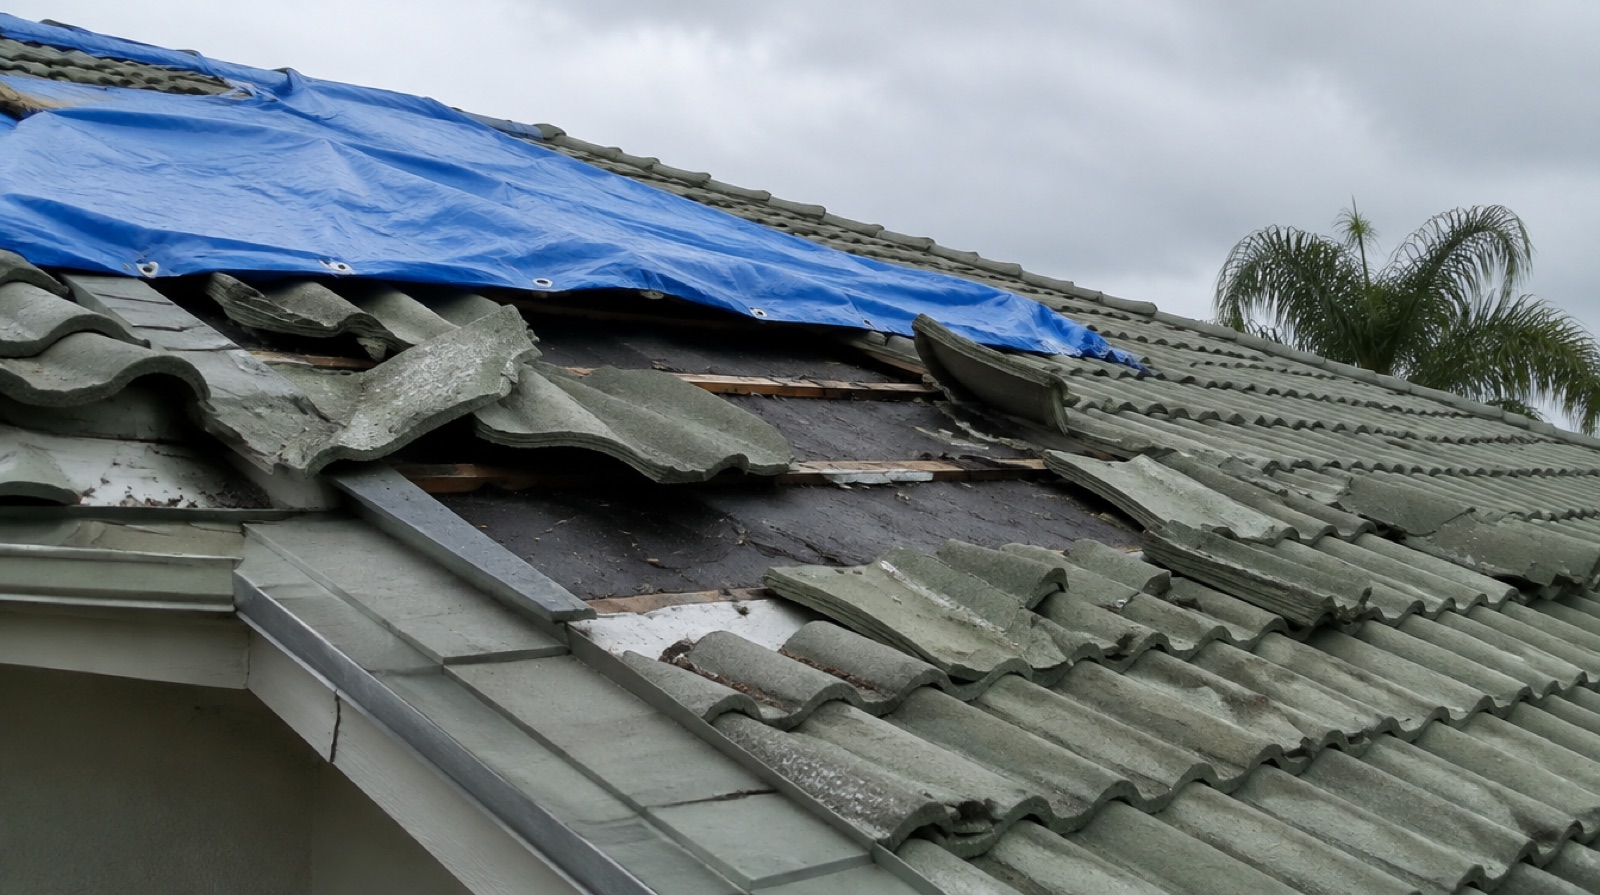
Insurance is designed to cover sudden and accidental damage, like storm or pipe burst events. It does not cover gradual maintenance issues. Insurers frequently blame legitimate, sudden storm damage on pre-existing wear and tear to avoid paying out.
2. “Late Reporting” Delays
Most policies require you to notify your insurer of damage within a “prompt” timeframe. If you wait too long even if you have a good reason, the insurance company may use the delay to deny the entire claim, claiming your delay made the damage worse.
3. “Insufficient Evidence” and Documentation
The burden of proof is on you. If your initial claim lacked clear photos, precise repair estimates, or proof of when the damage occurred, an automated system or rushed adjuster may simply reject it.
How to Appeal a Denied Property Damage Claim
If you disagree with your insurer’s decision, do not give up. Follow these three steps to build a strong appeal:
Step 1. Review the written denial:
Read the denial letter carefully. Your insurer is legally required to cite the exact policy language or exclusion they are using to reject your claim.
Step 2. Document everything:
Take high-resolution photos and videos of all damage. Keep every receipt for temporary repairs, water mitigation, or tarps. Secure an independent estimate from a licensed local contractor.
Step 3. Consult a property damage lawyer:
Insurance policies are complex legal contracts. A specialized attorney can review your policy, expose bad-faith tactics, and handle the negotiations to get your claim paid.
The Bottom Line: Your insurance company has teams of experts working to protect their bottom line. You deserve an experienced advocate fighting for yours.
Are you dealing with a denied property damage claim? Contact our office today for a free, no-obligation review. We will help you understand your options and fight to get your property fully restored.